

There are a number of reasons for which you may wish to buy a property with no kitchen, or a kitchen which doesn’t class as ‘functional’. You might want to renovate the property, for instance.
Learn more about what classes as a habitable property, a functional kitchen, and your options for securing a mortgage on the property.
Is a kitchen required for a mortgage?
A ‘functional kitchen’ is usually required in order to get most standard residential mortgage types. However, there are still a number of non-standard or alternative options if a property has no kitchen or is not considered ‘habitable’.
It’s useful to note that, for many lenders, the benchmark for what classes as a kitchen is relatively low. In many cases, a simple sink and worktop space screwed to a wall may pass a lender’s valuation.
What do lenders consider habitable?
When determining mortgage availability, lenders assess a range of factors to determine whether the house is ‘habitable’.
First of all, lenders look for basic amenities such as a functional kitchen (usually with a sink and running water), and an indoor bathroom with running hot/cold water. They also require utilities like central heating and functional electricity.
Next, they’ll look for structural integrity. This means that the roof, walls and windows need to be wind and watertight, and the home must be free of structural issues like subsidence or dampness.
Properties should also be secure, safe and hazard free.
Learn More about Mortgage Eligibility
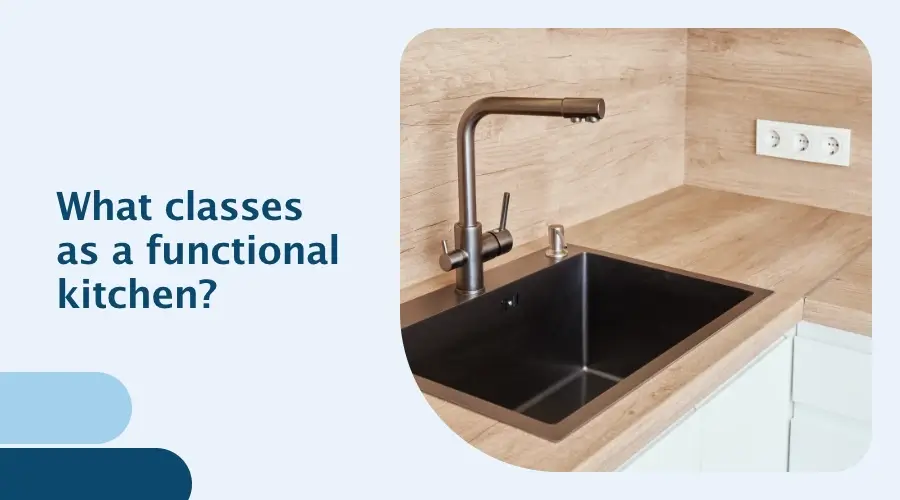
What classes as a functional kitchen?
For most standard mortgage products, a kitchen needs to meet certain requirements of functionality set by a lender. The fundamental requirements may vary based on the lender, but are usually as follows:
Water and waste - A working sink connected to both hot and cold water, plumbed for proper drainage.
Cooking facilities - The kitchen needs a safe and adequate place to cook food. This may simply be facilities to heat food/meals as opposed to a full luxury setup.
Safety and utilities - The facilities must be structurally sound, weathertight, and have working electricity, water and heating.
Food preparation space - There must be at least some space to prepare food on a worktop or counter.
Funding options for a property with no kitchen
There are a range of non-standard mortgage or funding options available for a property with no kitchen.
Renovation mortgages
You can utilise renovation mortgage products which are specifically designed for properties undergoing or in need of heavy renovation or refurbishment work. Instead of letting the full amount upfront, lenders will release funds in stages as the renovation work progresses.
To secure this mortgage type, you may need to provide an upfront plan of scheduled works, and prove you intend to carry out the work.
Bridging loans
Bridging loans are a common way to fund an ‘unmortgageable’ house purchase. These are secure short term loans which are lent against the future value of the property rather than its current state.
Lenders will provide quick access to money to use to buy the property and finance a kitchen installation. After this, you can remortgage onto a standard product.
Local authority grants
Depending on the current property situation (such as if it’s been empty for a while), you may qualify for local council funding. There are a number of government grants and schemes which cover the cost of renovations in order to make the property habitable.
To access these grants, you would need to apply directly to the housing or empty homes department, as well as submitting renovation plans and passing an inspection.
Negotiate with the seller
For currently occupied properties which don’t meet the requirements with a lender, you may be able to discuss a resolution before you buy the property. The seller may allow you to install a basic sink, worktop and cooking space between exchange and completion.
This may allow the property to be classed as habitable, opening up a number of lender options.
No kitchen mortgage support with Barlow Irvin
It’s not easy to navigate the process of getting a mortgage or funding for a property without a functional kitchen. With the support of expert mortgage advisors such as Barlow Irvin, we can help you understand the options available to you, and access the whole of the market, including specialist brokers.
Get in touch today for more information.
Get on Touch for Mortgage Support
As an FCA approved, whole-of-market broker, Barlow Irvin is able to compare products from a range of lenders, including specialist lenders, helping you find the best possible mortgage.